The Two-Tier Crypto Market: Bank Charters and DeFi Hacks
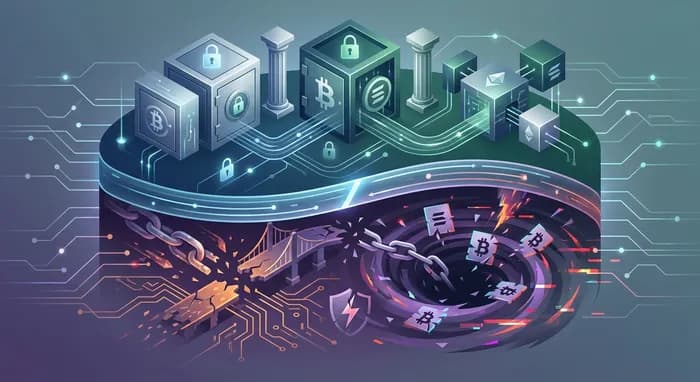
Early 2026 is producing a sharply split crypto market: regulated institutional rails are gaining legitimacy while DeFi is absorbing some of its worst exploit losses in years. This divergence is reshaping capital flows, accelerating crypto regulation debates, and forcing investors to rethink risk allocation across Institutional Crypto and permissionless protocols.
The center of gravity in crypto has shifted. In 2026, the market is no longer moving as one unified ecosystem: regulated venues, custody structures, and bank-like trust frameworks are attracting increasing institutional capital, while decentralized finance continues to wrestle with exploit risk, governance weaknesses, and uneven legal treatment.
That split matters because it is changing who participates, where liquidity settles, and how lawmakers are framing crypto policy. The bullish case is real: Bitcoin and Ethereum remain central to the digital-commodity conversation, and large U.S. crypto firms continue to pursue tighter integration with the banking system. But the risk story is just as real. DeFi exploit headlines have not disappeared, and every fresh loss reinforces the appeal of ring-fenced, supervised structures for allocators that cannot afford operational surprises.
Just as important, the regulatory backdrop is still unsettled. The CLARITY Act advanced in committee on April 28, 2026, but a legislative hold was placed by senators on May 1, 2026, stalling momentum. That means the market is not moving toward “imminent clarity”; it is moving through a live political fight over jurisdiction, consumer protection, and the future rules for decentralized systems.
A market increasingly divided between regulated rails and open protocols
The simplest way to understand crypto in 2026 is as a two-tier market.
In the first tier sit the structures that institutions can explain to boards, auditors, and regulators: qualified custody, trust entities, exchange surveillance programs, bankruptcy-remote arrangements where available, and products designed to fit into existing compliance frameworks. This is the segment benefiting from years of pressure for clearer supervision after the failures of the early 2020s.
In the second tier sits open DeFi: smart contracts, bridges, lending pools, perpetuals venues, and governance systems that still promise transparency and composability, but often expose users to code risk, oracle failures, governance capture, admin-key abuse, and cross-chain attack surfaces. The question is no longer whether DeFi innovation is real; it is whether enough capital believes the risk-adjusted return still justifies the exposure.
That divide is reinforced by policymakers’ approach to market structure. In the U.S., Congress continues to debate how digital assets should be classified and supervised, but the path is uneven rather than settled. Despite committee progress, the CLARITY Act is stalled following a legislative hold recorded on May 1, 2026, according to Congress.gov. The message for the market is clear: there is momentum, but there is also procedural resistance and no final resolution yet.
For asset managers, family offices, and corporate treasury teams, this uncertainty has a practical effect: capital tends to prefer assets and intermediaries that look more legible under existing law, even while the broader framework remains incomplete.
Why trust frameworks and charter-like structures matter more in 2026
A major reason the “safer tier” is gaining share is that leading firms have continued to push deeper into regulated infrastructure. That includes trust-company and custody models designed to satisfy fiduciary, segregation, and supervisory expectations in ways that pure exchange models historically did not.
For institutional allocators, the attraction is straightforward. A trust or bank-like framework may offer stronger operational controls and a more familiar legal structure. Even when those structures do not eliminate market risk, they can reduce operational, counterparty, and asset-handling risk.
The broader lesson matters more than any single corporate milestone: smart money is increasingly distinguishing between crypto as an asset class and crypto as an infrastructure stack. Many investors remain interested in the asset class while becoming far more selective about where and how they gain exposure.
That does not mean regulated crypto is risk-free. It means institutions are increasingly willing to pay for legal clarity, custody assurances, and governance standards. In a market still shaped by exploit headlines and incomplete legislation, regulated wrappers are not just conveniences; they are becoming the default access point for larger pools of capital.
DeFi’s exploit problem has not gone away — and that is shaping capital flows now
If the regulated side of crypto is defined by convergence with traditional finance, DeFi in 2026 is still defined by a persistent security discount.
Monthly loss figures often vary by blockchain security firm, methodology, and cutoff date, so any large number should be treated carefully unless tied to a specific report. What is beyond dispute is the broader present-tense reality: major exploits, bridge attacks, governance compromises, wallet drains, and smart-contract vulnerabilities are still occurring often enough to keep risk committees on edge.
That matters because frequency can be more damaging than any single incident. Repeated losses can undermine user confidence. For retail users chasing yield, the effect is brutal: the headline APY may look attractive, but a single exploit can erase years of incremental return.
In other words, DeFi is not merely suffering from isolated hacks; it is grappling with a structural trust problem. Each exploit widens the spread between what permissionless finance can offer in theory and what mainstream capital is willing to tolerate in practice.
That is why the market’s response has been rational: institutions are not abandoning crypto altogether, but they are increasingly limiting direct exposure to unaudited or operationally complex DeFi systems. Instead, they are favoring listed products, large-cap spot exposure, custodial solutions, and counterparties with clearer control environments.
What exploit persistence means for retail and professional investors
For retail participants, the 2026 environment argues for a stricter distinction between speculative yield and core allocation. Funds used for long-term portfolio exposure are increasingly better housed in simpler, more transparent vehicles than in complex DeFi strategies dependent on multiple contracts, bridges, and governance assumptions.
For professional investors, exploit persistence reinforces three practical truths:
- Smart-contract risk is not diversifiable in the same way market beta is. Correlated design patterns can fail across protocols.
- Operational due diligence matters as much as token analysis. Admin keys, upgradeability, oracle dependencies, and cross-chain architecture are central risks.
- Liquidity can disappear when confidence breaks. A protocol can look healthy until an exploit, governance dispute, or freeze event changes user behavior overnight.
That is why security incidents are not just technical problems; they are asset-allocation events.
How stalled legislation is influencing strategy right now
The fight over crypto market structure is no longer abstract. Legislative timing now affects product design, go-to-market decisions, and where firms choose to domicile functions such as custody, listing, staking, and protocol access.
The current status of the CLARITY Act is a good example. After committee movement on April 28, the bill encountered a legislative hold on May 1, 2026. That means firms cannot treat it as enacted policy. They have to operate in a world where progress is visible, but delay is real.
This matters especially for DeFi because any eventual framework is likely to revisit difficult questions that remain unresolved today: when a protocol is sufficiently decentralized, who bears compliance obligations, how front ends should be treated, what disclosures should be required, and how regulators should handle governance tokens and fee rights.
For now, the result is strategic caution. Centralized firms continue building toward regulated products because those can usually be mapped onto existing supervisory models more easily than permissionless systems can. DeFi builders, by contrast, face a harder challenge: improving security and decentralization while also preparing for legal expectations that may arrive gradually and unevenly.
So the Senate battle is important, but the immediate investment takeaway is simpler: do not confuse legislative relevance with legislative finality. The market is adapting to uncertainty, not waiting for perfect clarity.
What to watch next in Washington
Investors should focus on process, not just headlines. Key markers include whether the legislative hold is lifted, whether a revised version of the bill emerges, whether Senate leadership allocates floor time, and whether competing proposals reshape the jurisdictional balance between regulators.
Until one of those changes occurs, the most accurate description is that crypto market-structure reform remains active but unresolved. That unresolved status supports the current bifurcation of the market: capital with strict mandates keeps clustering around the most regulated touchpoints, while higher-risk capital continues to experiment in less protected environments.
Actionable portfolio takeaways for a two-tier crypto market
For investors and operators, 2026 is a year to be deliberate rather than ideological. The market is rewarding risk segmentation.
1. Separate core crypto exposure from experimental exposure. Treat large-cap spot positions, regulated funds, and institution-grade custody as the core bucket. Treat DeFi yield strategies, newer chains, bridges, and governance-token trades as a separate high-risk bucket with explicit loss limits.
2. Underwrite infrastructure, not just assets. Before allocating, ask who controls upgrades, how keys are managed, whether audits were repeated after code changes, how oracle dependencies work, and what incident-response procedures exist.
3. Assume legal timelines can slip. The CLARITY Act’s current stalled status is a reminder that even high-visibility bills can slow down abruptly. Structure strategy around today’s rules and current enforcement realities, not around hoped-for legislation.
4. Favor ring-fenced structures when fiduciary duties are strict. If the capital belongs to clients, treasury operations, or a formal investment committee, the burden of proof for using open DeFi should be much higher than for using supervised custody and clearer legal wrappers.
5. Demand a security premium from DeFi. Permissionless yield should only be attractive if it compensates for exploit risk, smart-contract complexity, and liquidity fragility. If the spread over safer alternatives is modest, the trade may not be worth it.
6. Build scenario plans. Model outcomes for exploit events, protocol freezes, delayed withdrawals, enforcement shifts, and legislative stalls. In 2026, crypto strategy is as much about resilience as return.
Conclusion
The crypto market in 2026 is not dividing because innovation has stopped; it is dividing because risk is being priced more realistically. Regulated custody, trust-style structures, and institution-friendly access points are gaining ground because they solve problems that large allocators actually have. At the same time, DeFi remains innovative but operationally fragile enough that many investors now treat it as a satellite exposure rather than a core holding.
The most important update is legislative as much as technological: the CLARITY Act is not cruising toward resolution. After its April 28 committee success, it was stalled by a legislative hold on May 1, 2026. That current status reinforces the broader theme of the year: capital is not waiting for perfect clarity. It is moving toward the parts of crypto that already look governable, auditable, and survivable—and away from structures that still demand a higher tolerance for operational and legal uncertainty.