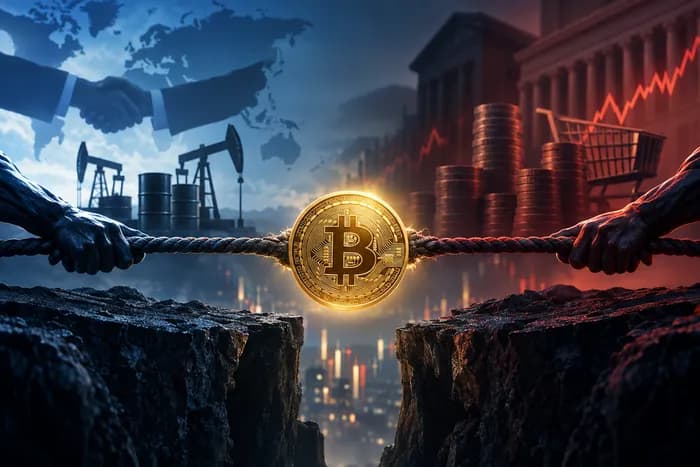
Bitcoin’s Macro Tug-of-War: Geopolitics vs. Inflation
This Bitcoin macro analysis examines how U.S.-Iran diplomacy, sticky inflation and nearly $1 billion in Bitcoin ETF outflows are overpowering traditional Uptober market trends. Learn which indicators investors should monitor as conflicting macro forces keep BTC price action volatile.
Bitcoin is being pulled between competing macro forces. Progress in U.S.-Iran diplomacy could reduce geopolitical risk, ease pressure on energy markets, and support a relief rally in risk assets. At the same time, hotter inflation and persistent institutional outflows are making a sustained upside move more difficult.
A prior example illustrates the mechanism. On April 14, 2026, CNBC reported that Bitcoin was approaching $71,000 as hopes for U.S.-Iran talks pushed oil lower. That episode is historical, not a description of today’s price action. Still, it shows the transmission channel investors continue to watch: diplomacy can reduce the perceived oil-supply risk premium, ease inflation concerns, and improve risk appetite.
That channel has limits. As of October 19, 2026, the diplomatic opening remains conditional, while fresh U.S. inflation data and Bitcoin ETF outflows are exerting more measurable pressure. The result is a headline-sensitive market in which rallies can emerge quickly but struggle to secure lasting institutional follow-through.
Geopolitical Relief Has Limits
The bullish case for crypto begins with oil. When markets believe conflict may de-escalate or energy shipments may normalize, crude prices can retreat as traders remove part of the geopolitical risk premium. Lower oil prices can reduce expected transportation and production costs, ease inflation fears, and improve demand for risk-sensitive assets such as Bitcoin.
However, investors should distinguish between negotiations and an agreement. On October 18, Iran said its proposal to reopen the Strait of Hormuz remained available, but Reuters reported that the United States and Iran were still divided over sanctions, the U.S. blockade, and nuclear concessions. Under the proposal, Washington would need to accept Tehran’s conditions before the strait could reopen. The issue therefore remained unresolved as of October 19, 2026.
That distinction matters because unresolved shipping access can preserve the oil-risk premium that diplomatic headlines might otherwise remove. The latest U.S. Energy Information Administration outlook expects oil prices to decline from their early-October average, although its forecast was revised higher from the prior month. This combination—expected moderation alongside elevated uncertainty—suggests that energy may provide intermittent relief rather than a clear bullish catalyst for crypto. The EIA’s October outlook supports a cautious interpretation: lower oil prices are possible, but the geopolitical risk premium has not disappeared.
Why Bitcoin Reacts to Oil Headlines
Bitcoin trades continuously and has become a liquid vehicle for expressing changes in global risk appetite. An encouraging diplomatic headline can trigger crypto buying before traditional markets fully reopen. The reverse is equally important: failed talks, disrupted shipping, or renewed escalation can lift oil prices and inflation expectations, strengthen defensive positioning, and accelerate BTC selling.
Investors should therefore avoid treating every diplomatic headline as a structural trend change. Confirmation should come from tangible improvements in energy flows, sustained declines in crude prices, lower bond yields, and improving spot-market demand.
Inflation Is the Stronger Counterweight
While geopolitical relief can support short-term rallies, fresh inflation data are challenging the case for a durable crypto advance. The Bureau of Labor Statistics reported on October 14 that September consumer prices rose 0.6% month over month and 3.7% year over year. Gasoline increased 9.1% during the month and accounted for more than half of the headline CPI increase. Core prices, excluding food and energy, rose 0.3% monthly and 2.6% annually.
Wholesale inflation delivered an even stronger warning. The October 15 Producer Price Index release showed final-demand prices rising 1.3% in September—the largest monthly increase since March 2022—and 6.3% from a year earlier. Final-demand energy jumped 10.8%, while gasoline surged 20.3%.
These figures complicate the outlook for interest rates and, by extension, crypto markets. Hot inflation gives policymakers less room to ease monetary conditions and can lead markets to price in a longer period of restrictive rates—or potentially additional tightening. Higher expected rates can lift Treasury yields and increase the opportunity cost of holding non-yielding assets.
Bitcoin may function as a long-term hedge against monetary debasement, but over shorter horizons it often behaves like a high-beta liquidity asset. If an inflation surprise pushes real yields and the dollar higher, BTC can fall even when its long-term scarcity argument remains intact. Nationwide economist Oren Klachkin characterized the latest producer-price report as reinforcing the message that inflation was moving in the wrong direction for the Federal Reserve, according to Axios on October 15. That is the immediate macro challenge for Bitcoin bulls.
ETF Outflows Undermine Uptober
Institutional liquidity is the third force shaping BTC price action. More recent flow data show that spot Bitcoin ETFs recorded approximately $910 million in net outflows over two weeks: $681.1 million in the first week and another $228.6 million in the second. That is nearly $1 billion in withdrawals, contradicting the historically bullish “Uptober” pattern that many traders expected to support prices.
Bitcoin funds recorded $82.4 million in outflows on the reported Friday, while October’s cumulative net flows had fallen to approximately negative $615 million after an initially positive start, according to Decrypt’s October 18 report.
ETF flows matter because these products connect traditional portfolios directly to spot Bitcoin exposure. Persistent redemptions do not mean every institution has turned bearish, and the funds retain substantial cumulative inflows from prior periods. Nevertheless, outflows remove a dependable source of marginal demand. Depending on how redemptions are processed and hedged, they may also contribute to spot selling or reduce demand for inventory among authorized participants.
This helps explain why relief rallies have struggled to become durable breakouts. Geopolitical optimism may generate short covering and tactical buying, but continued ETF outflows suggest that larger pools of capital are not consistently validating the move. Seasonality alone cannot compensate for a sustained liquidity drain.
Why Bitcoin Remains Range-Bound
Bitcoin remains range-bound because short-term diplomatic relief is being offset by higher-rate expectations and weaker institutional demand. These catalysts also operate on different time horizons: diplomatic optimism can move prices within minutes, inflation affects rate expectations over months, and ETF flows reveal institutional allocation each trading day.
A bullish breakout would likely require several signals to align: tangible progress in U.S.-Iran talks, sustained energy-price moderation, softer inflation readings, lower Treasury yields, and a return to consistent ETF inflows. A bearish breakdown becomes more probable if talks fail, oil rebounds, yields rise, and ETF redemptions continue.
Until that alignment appears, investors should expect false breakouts. Bitcoin can rally sharply on geopolitical relief without establishing a durable uptrend, while inflation-driven declines can become exaggerated if derivatives leverage is flushed. The range is therefore not evidence that macro conditions are irrelevant; it is evidence that powerful macro forces are offsetting one another.
An Actionable Investor Framework
Investors navigating this environment should prioritize confirmation over narrative.
- Track ETF flows daily and weekly. One positive session matters less than a multi-day reversal in cumulative flows.
- Watch the inflation pipeline. CPI captures consumer prices, while PPI measures pipeline-cost pressure that may feed through to consumer prices. Persistent strength in both is more consequential than one isolated report.
- Monitor oil alongside yields. Falling crude is most constructive for Bitcoin when inflation expectations, Treasury yields, and ideally the dollar are also declining.
- Treat diplomacy as conditional. Until an agreement is signed and implemented, negotiations remain a volatility catalyst rather than a resolved bullish event.
- Reduce dependence on calendar effects. Uptober is a historical tendency, not a risk-management system. Real-time liquidity and macro data should take precedence.
Bitcoin may be the macro bellwether, but portfolio-level risk can be greater in smaller tokens. Token-level analytics can complement this framework by monitoring liquidity concentration, volatility, holder behavior, and deteriorating market depth. In a macro-driven sell-off, tokens with weak liquidity or concentrated ownership may experience much larger drawdowns than Bitcoin. Portfolio decisions should therefore combine top-down macro analysis with bottom-up crypto risk evaluation.
Conclusion
Bitcoin’s macro tug-of-war is not simply geopolitics versus inflation. It is a contest between potentially temporary geopolitical relief and persistent financial pressure. U.S.-Iran diplomacy may reduce oil-related risk, but negotiations remained unresolved as of October 19, 2026. Meanwhile, 3.7% headline inflation, a 6.3% annual rise in producer prices, and approximately $910 million in two-week ETF outflows provide concrete reasons for institutional caution.
For investors, the central lesson is to avoid trading narratives in isolation. A durable bullish move needs geopolitical improvement to be confirmed by lower yields and renewed institutional inflows. Until then, disciplined position sizing, liquidity monitoring, and data-driven risk analysis are more valuable than reliance on seasonal optimism.