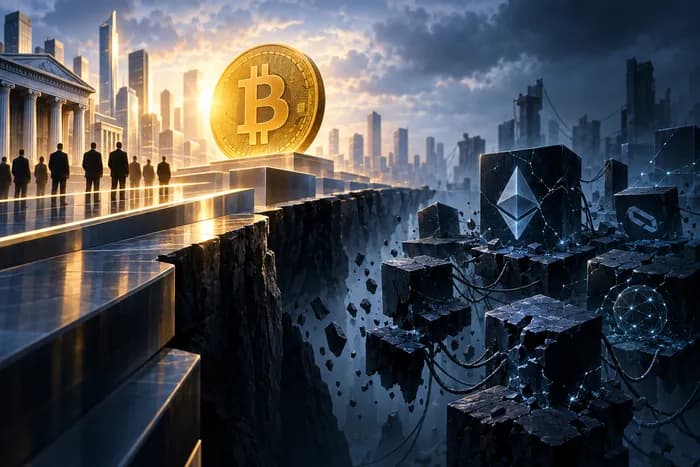
Bitcoin's Bull Run Masks Web3's Growing Infrastructure Crisis
Bitcoin ETF inflows and Citigroup's $113,000 BTC target signal accelerating institutional adoption, but collapsing Layer-2 economics and $1.26 billion in quarterly exploits expose a widening Web3 infrastructure crisis.
Bitcoin's 40% third-quarter rally appears to confirm crypto's arrival as an institutional asset class. ETF capital is returning, Wall Street price targets are rising, and regulated products are giving traditional allocators exposure without requiring direct interaction with blockchains or decentralized finance (DeFi).
Beneath that bullish headline, however, parts of the industry's operating layer are under serious strain. The Blast network shutdown, deteriorating economics among smaller chains, and a quarter marked by hundreds of security incidents suggest that institutional crypto adoption and on-chain health are not advancing at the same pace. Investors are increasingly confronting a two-tiered market: Bitcoin and a handful of established platforms attract capital, while smaller decentralized projects struggle to retain users, generate revenue, and maintain security.
Bitcoin's Rally Was Driven by Institutional Access
Bitcoin ended Q3 2026 up 40%, outperforming major traditional assets even as Treasury yields reached their highest levels in more than 20 years, according to an October 1 CoinDesk market report. That resilience suggests that Bitcoin is benefiting not only from broader market conditions, but also from demand for a liquid, institutionally accessible digital asset.
Bitcoin ETF flows were central to the move. U.S. spot Bitcoin ETFs had recorded $5.8 billion in year-to-date outflows by July 13, but subsequent demand reversed the deficit, bringing net inflows for 2026 to approximately $800 million by late September. Citigroup expects these flows to become “slower but stickier” as advisers and brokerages gradually increase allocations rather than chase short-term momentum, according to its forecast reported October 1.
Supportive macroeconomic conditions amplified this institutional demand. Treasury purchases of longer-dated bonds eased market pressure, while improving sentiment helped crypto recover from a period of underperformance relative to other risk assets. But ETFs explain an important feature of the rally: much of the new demand can gain Bitcoin exposure without moving into the on-chain economy.
The Citigroup BTC Target Reflects a Structural Shift
Citigroup raised its 12-month Bitcoin price target from $82,000 to $113,000 and its Ether price target from $2,240 to $3,028. The bank also projected $5 billion in total inflows to crypto investment products over the following 12 months, as detailed in the October 1 report.
Citigroup's BTC target is notable less for its exact price than for what underpins it: institutional access. ETFs remove several operational burdens associated with direct ownership, including private-key management, blockchain bridging, protocol selection, and smart-contract exposure. They allow investors to gain Bitcoin exposure through regulated accounts and familiar custodial structures.
This creates an important distinction. Capital flowing into a Bitcoin ETF enters the broader digital-asset market, but it does not necessarily support Web3 infrastructure. It may never reach Layer 2 networks, decentralized exchanges, lending protocols, or application tokens. Institutional demand can therefore lift BTC—and, to a lesser extent, ETH—without improving the revenue or user activity of smaller on-chain ecosystems.
ETFs do not cause these ecosystems to weaken. Rather, they allow institutional adoption to expand without solving the economic and security problems that smaller networks already face. That distinction becomes clearest in the economics of independent Layer 2 networks.
Blast Illustrates the Pressures Driving Layer 2 Consolidation
Blast illustrates the other side of this market. The Ethereum Layer 2 once held more than $2 billion in assets, but its total value locked (TVL) fell to approximately $32 million. Its BLAST token fell about 98% from its launch price, while network revenue dropped from roughly $3.5 million in June 2024 to just $1,793 in September 2026, according to the October 2 shutdown report.
Blast's team concluded that maintaining the network cost substantially more than it generated in revenue and that it had no credible path to economic sustainability. Users have until October 26, 2026, to withdraw assets to Ethereum through Blast's interface. After that date, withdrawals will require direct interaction with the bridge contracts.
This is not simply a failed-token story. It is a vivid example of the pressures driving Layer 2 consolidation. Networks must continually fund development, infrastructure, security, liquidity incentives, ecosystem grants, and user acquisition. When speculative deposits leave, those fixed and semi-fixed costs remain.
Meanwhile, centralized companies possess advantages that native protocols often lack. Coinbase can direct customers and developers to Base, while Robinhood can connect its existing distribution network to an Ethereum-based chain. Established brands, embedded user bases, and multiple revenue streams can lower customer-acquisition costs and give these platforms more capacity to subsidize growth. Independent Layer 2 projects must compete without those advantages. The likely result is fewer viable networks and more activity concentrated around corporate-backed ecosystems.
Crypto Hacks Reveal the Industry's Hidden Liability
The economic pressure on Web3 infrastructure is compounded by persistent security failures. During Q3, the crypto sector recorded 247 security incidents and lost $1.26 billion to hacks and exploits. September was the worst month of 2026, with 99 incidents causing $768.5 million in losses, according to the October 1 security analysis.
The contrast is stark: Bitcoin gained 40% during the same quarter in which attackers extracted more than $1 billion from the broader ecosystem. These incidents did not prevent ETF investors from buying BTC because regulated wrappers largely insulate them from DeFi's technical complexity. Native users, however, remain exposed to smart-contract bugs, compromised interfaces, bridge vulnerabilities, operational mistakes, and increasingly automated attack methods.
Security costs intensify the infrastructure squeeze. Smaller protocols facing falling revenue cannot safely treat audits, monitoring, incident response, and developer retention as optional expenses. Yet spending more on security worsens already difficult unit economics. Spending less can create catastrophic tail risk. In this way, weak economics and security risk reinforce one another: declining revenue constrains security spending, while security failures undermine trust, retention, and future revenue.
Investors should therefore treat token price as only one indicator of a project's health. A stronger framework also examines recurring protocol revenue, treasury runway, security history, dependence on incentives, user concentration, bridge design, withdrawal conditions, and whether a network can cover its operating costs without continuous token issuance. On-chain analytics and risk-monitoring tools can help investors identify these interconnected signals before market enthusiasm obscures structural weakness.
How Investors Should Navigate the Two-Tier Market
The emerging divide does not mean investors should abandon Web3. It means they should stop assuming that a Bitcoin bull market automatically validates every blockchain, Layer 2, or DeFi token. Institutional flows may concentrate in a narrow group of assets while the rest of the market continues consolidating.
Investors evaluating Web3 infrastructure should prioritize sustainable fee generation over headline TVL, because deposits driven by airdrop expectations can disappear quickly. They should compare revenue with security and operating costs, scrutinize token-unlock schedules and dependence on incentives, and determine whether users have safe exit paths if a network winds down.
Concentration risk deserves equal attention. Corporate-backed networks may offer stronger distribution and longer financial runways, but they can also introduce governance, censorship, and strategic-dependency risks. Independent protocols may preserve greater neutrality while carrying higher financial and execution risk. Portfolio construction should reflect that trade-off rather than treating all Layer 2 exposure as interchangeable.
Finally, investors should separate asset-level conviction from ecosystem-level conviction. A bullish view on Bitcoin can coexist with caution toward smaller infrastructure tokens. In the current market, that distinction is not inconsistency; it is disciplined risk analysis.
Conclusion
Bitcoin's Q3 performance, renewed ETF demand, and Citigroup's $113,000 price target suggest that traditional finance is gaining a durable foothold in digital assets. Yet the Blast network shutdown and $1.26 billion lost to quarterly exploits show that smaller and weaker Web3 ecosystems have not matured at the same pace as institutional access.
The market's next phase may reward scarcity, distribution, durable revenue, and security more than broad crypto beta. Investors should look beyond price momentum and evaluate whether a protocol can retain users, fund operations, withstand attacks, and survive after incentives fade. Bitcoin's bull run is real—but so is the growing infrastructure strain it can obscure.